Equal-Payment Versus Equal-Principal Loans
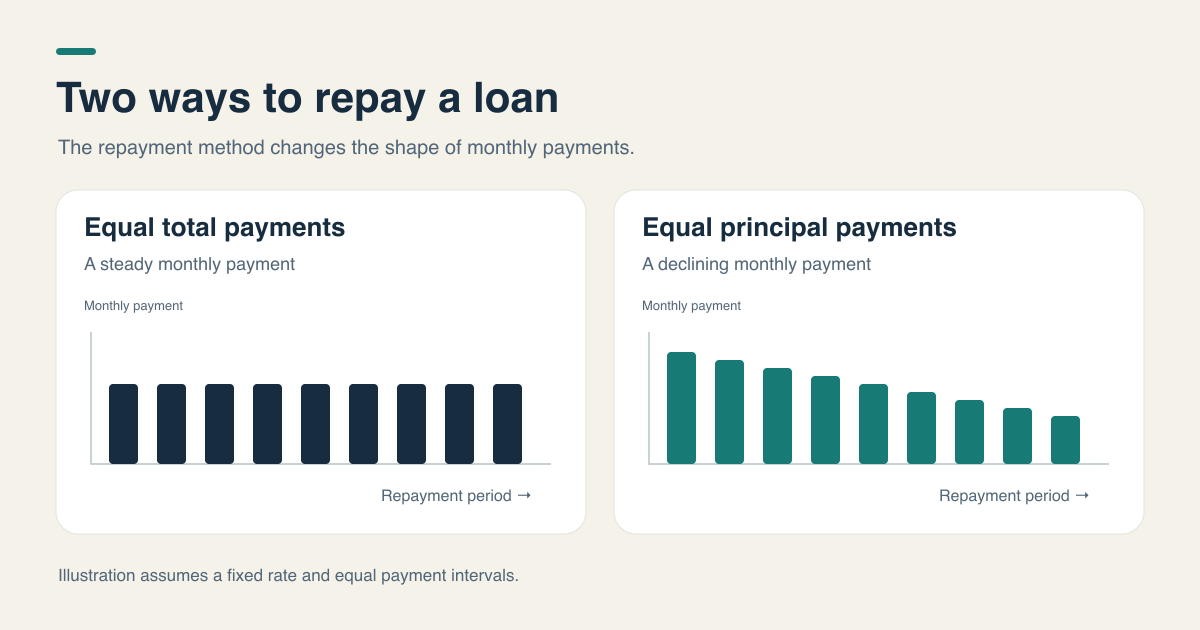
Hold principal, rate and term constant to compare level total payments with level principal repayments. Equal principal can start with a larger bill because its interest decreases as the balance falls.
Jump to calculator ↓- Runs in your browser
- Nothing is uploaded
- No signup; device limits apply
Loading the tool. If it does not appear, reload this page.
How to use this tool
Enter KRW principal, years and annual percentage. Keep those inputs fixed when changing repayment method to isolate the effect of the repayment structure.
Results and examples
The equal-principal headline is the first instalment. Only the first twelve rows are shown, but total interest covers the full term, so summing visible rows will not necessarily reproduce it.
Worked example
KRW 12 million over one year at 0% gives KRW 1 million monthly with either method.
Limitations
- Daily accrual, prepayment, variable rates and fees are excluded.
- Actual payment dates and bank rounding may differ.
Fields
| Field | Guidance and constraints |
|---|---|
| Loan amount (KRW) | Check the unit and format displayed beside this field. |
| Term (years) | Check the unit and format displayed beside this field. |
| Annual interest rate (%) | Check the unit and format displayed beside this field. |
| Equal principal and interest | Check the unit and format displayed beside this field. |
| Equal principal | Check the unit and format displayed beside this field. |
Data handling
Processing stays in the current browser tab; the site does not upload tool input for the calculation itself.
Sources
Frequently asked questions
Is the equal-principal monthly figure constant?
At zero interest, payments stay the same each month. At a positive fixed rate, interest and monthly payments decrease after the first payment shown.
Does a twelve-row table mean a one-year term?
No. Display is limited to twelve rows while totals cover the entered term.
Related tools
You do not need to start over. Continue with the tool that fits your next step.